Vol. 1, No. 7Friday, October 23, 2026Not a real newspaper

The 401(k) Liar

America's Least Trusted Source for Retirement Plan News

Access Edition
The 401(k) Liar StoreOur commitment to independence now comes in several sizes.Shop the collection →

Breaking · Private Markets

Private Equity, Having Run Out of Rich People, Discovers 20-Person Plumbing Company

Firm confirms every wealthy person in America has been contacted.

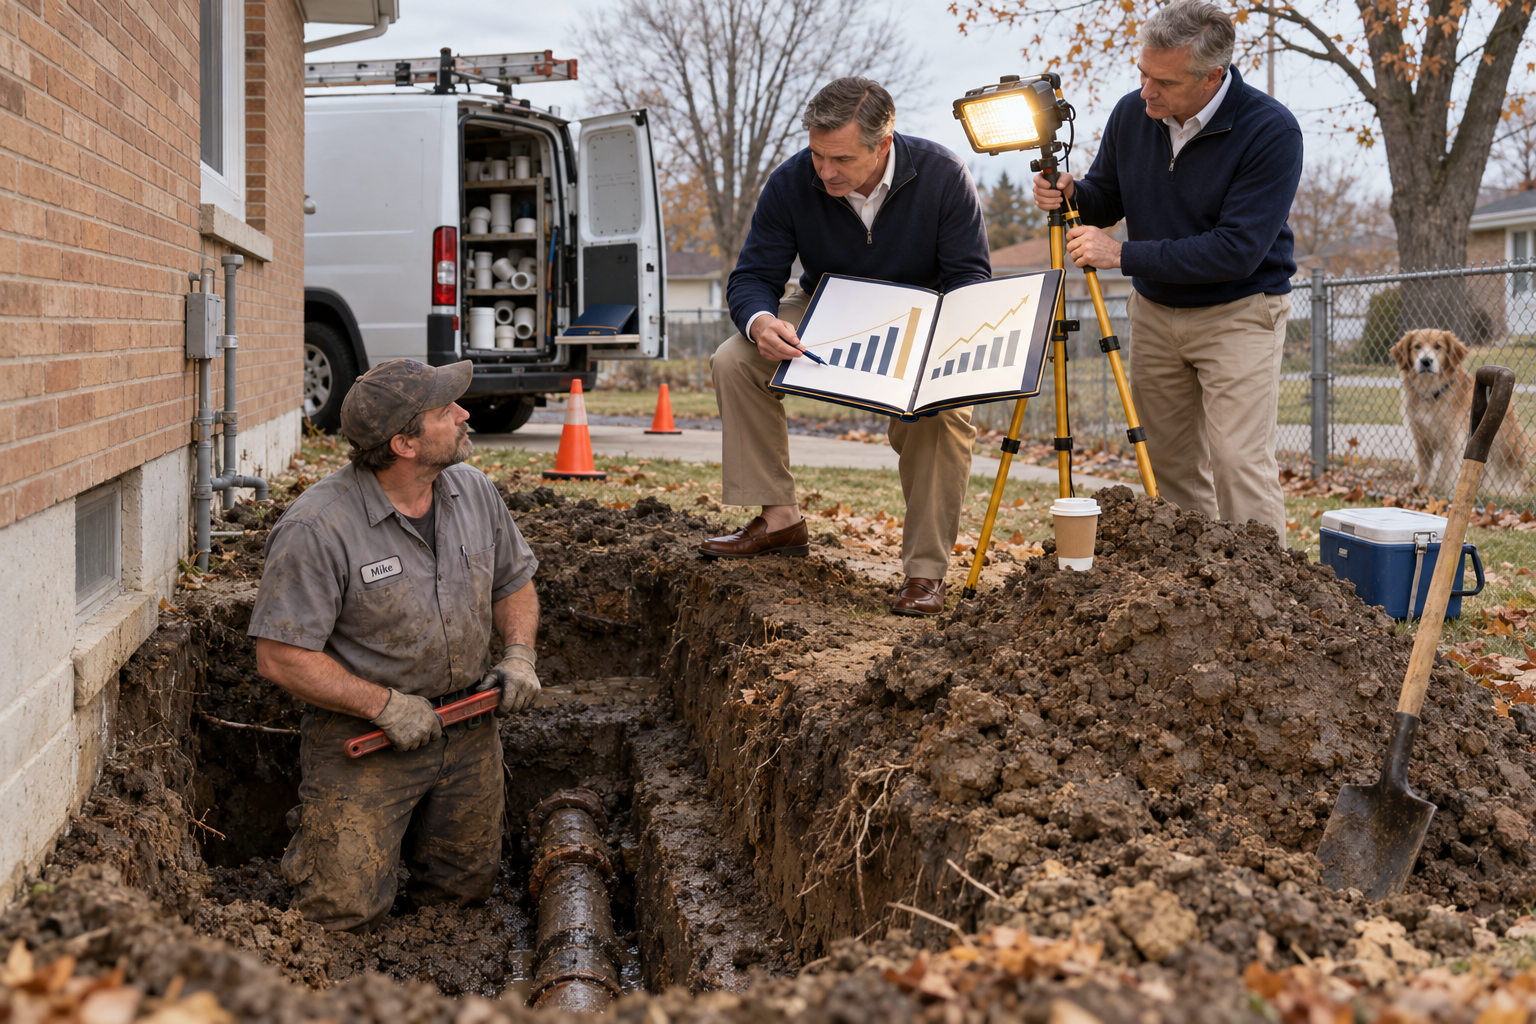
Two private-equity partners in quarter-zip pullovers and loafers stand at the edge of a muddy sewer-line excavation beside a brick ranch house, holding a glossy pitch book of bar charts open downward toward a plumber standing waist-deep in the trench with a pipe wrench. One partner holds a tripod work light so the pages can be read. A plumbing van is parked in the driveway; a dog watches through the fence.
Thornbury partners present the fund to a Kowalski technician Thursday. Both parties described the asset as illiquid.AI-generated satirical photo illustration

Thornbury Capital Partners, the $380 billion private-equity firm, announced Friday that it has identified a new source of capital in the 20 employees of Kowalski Plumbing & Heating of Toledo, Ohio, after confirming that every wealthy person in the United States had already been contacted.

“The family offices see the number and don’t pick up,” said Thornbury partner Graham Whitlock. “Kowalski picked up on the second ring.”

Owner Dan Kowalski, 58, said the partners used the word “illiquid” eleven times in the first ten minutes.

“I told them that’s most of what we fix,” Kowalski said. “They wrote that down.”

“I told them that’s most of what we fix. They wrote that down.”— Dan Kowalski, Owner, Kowalski Plumbing & Heating

Whitlock said the firm’s funds, which have historically required a $5 million minimum and a ten-year commitment, were a natural fit for a workforce that already understands things being stuck. “These are people who deal with a blockage every day,” he said. “They don’t panic. They don’t ask when it will clear. That is our investor.”

Kowalski said his technicians generally clear a blockage within the hour. Whitlock said the fund’s timeline was different but the principle was the same.

Kowalski asked how long until the money comes out. Whitlock said ten years.

Kowalski said he would send a truck.


Two Chairs · The Same Six Questions

Firm Keeps 5 Percent of Gains, Participant Keeps 100 Percent of Losses; Partnership Announced

The arrangement — Fulcrum, a New York retirement startup, arranges four dollars of financing for every dollar a participant saves, invests the total, and keeps five percent of the gains when the money comes out. The Liar put the same six questions to Fulcrum chief executive Evan Marsh and to Fulcrum participant Marcus Bell, 41, a forklift operator in Dayton, Ohio. Both described the partnership as a good one.

  • How does the partnership work?

    FulcrumFor every dollar Marcus saves, we arrange four more. The portfolio earns about 9 percent. The financing costs about 6.25. The difference is his.

    Marcus BellThey said it’s like a mortgage. I have one of those. It’s going fine.

  • And the fee?

    FulcrumWe keep 5 percent of the gains at withdrawal. We think that aligns us.

    Marcus BellFive percent of the gains. So most of the gains are mine. I did that math in the parking lot.

  • What happens if the investments go down?

    FulcrumMarcus is responsible for the financing. That’s standard.

    Marcus BellI’m responsible for the financing. That’s the one I’d want to read again.

  • Who chose the investments?

    FulcrumMarcus did, from a menu.

    Marcus BellThere was a menu. It had one thing on it, and it was checked.

  • Did Marcus opt in?

    FulcrumNinety percent of users do.

    Marcus BellI remember a button.

  • How would you describe the partnership?

    FulcrumAligned. We only win when Marcus wins.

    Marcus BellThey only win when I win. That’s the part I keep coming back to. What about the other times?

Fulcrum said the other times are covered in the agreement. Bell said he would look for it.


Around the Industry

Man Borrows Against Retirement to Fund Retirement; Both Pleased

Dale Hemmer, 52, took a $14,000 loan from his 401(k) Tuesday to cover household expenses while increasing his payroll contributions by the same amount, an arrangement he described as “getting the match.”

The loan will be repaid over five years at an interest rate Hemmer pays to himself, which he said was the part that sold him. “I’m a good borrower,” he said. “I know the guy.”

Human resources processed the loan on Monday and the savings increase on Tuesday. Different departments reported progress.

His 401(k) could not be reached for comment. It was busy on both sides of the transaction.

Hemmer plans to do it again when the loan is paid off, which he said was up to him.

Scottsdale Advisor Explains Illiquidity to Clients Using Timeshare He Cannot Sell

Financial advisor Brent Kessling, who added a private-markets fund to three client lineups this month, held an education session Wednesday to make sure participants understood a ten-year lockup. He brought the deed.

“I bought this in 2011,” Kessling said, holding up a brochure for a two-bedroom unit in Lake Havasu City. “I have been trying to sell it since 2013. That is illiquidity.”

A participant asked whether the fund would at least go up in value. Kessling said that was a separate conversation and that he had maintenance fees to cover first.

Participants reported understanding illiquidity completely. Three asked how to get out of the fund.

Kessling said that was the lesson.